From Paralegal to Bail Agency Owner: Turning Courtroom Experience Into a Business
Paralegal experience can provide a strong foundation for running a bail agency, but court knowledge is only part of the job. A responsible transition also requires licensing, financial controls, clear client communication, reliable case tracking and firm boundaries around collections and recovery.
By Bail Bonds Magazine Staff
Oct 25, 2026 · 6 min read
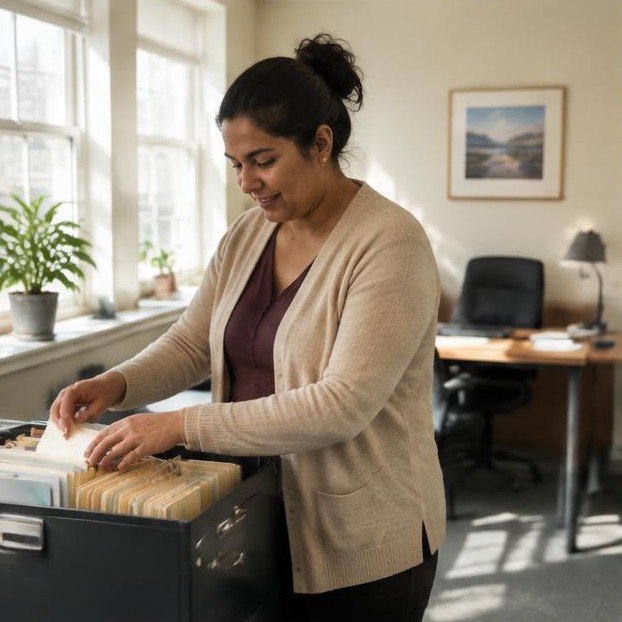
A paralegal considering bail agency ownership already understands something essential: a court file is not just paperwork. It connects a person, a family, a calendar and consequences that can become expensive when someone misses a detail. That perspective can help an aspiring owner build a careful operation. It does not, however, substitute for a bail license, underwriting judgment or the ability to manage a business after the courthouse closes. The real transition is from supporting legal work to accepting responsibility for client service, financial exposure and regulated transactions. For someone making that move, the useful question is not whether courtroom experience transfers. It is which skills transfer directly, which require additional preparation and which responsibilities need qualified outside help.
Courtroom Knowledge Is an Advantage, Not a Business Plan
Consider a hypothetical paralegal who has spent years organizing criminal case files and communicating with court staff. She knows how to identify a case number, distinguish a hearing notice from an order and recognize when a document needs an attorney’s attention. When she considers opening a bail agency, those habits give her a practical starting point. She is comfortable checking records rather than relying on a caller’s memory, and she understands why a changed court date must reach the right person.
But her new role would be different. A bail agency must evaluate whether it can responsibly write a bond, explain contractual obligations, account for payments and collateral, and maintain service when the owner is unavailable. Familiarity with criminal procedure does not answer whether an agency has enough working capital or whether its staffing plan can support overnight inquiries.
The first planning exercise should separate existing skills from untested assumptions. Document management may be a strength. Cash-flow planning, surety relationships, consumer disclosures and supervision may need work. An honest assessment is more valuable than treating legal-office experience as proof of readiness.
Establish Authority Before Accepting Business
Licensing comes before marketing a service as available. In California, prospective owners should verify current requirements with the California Department of Insurance and determine which individual and business approvals their proposed operation needs. Ownership, licensed activity and authority to transact business should not be assumed to mean the same thing. The structure of the agency and its proposed services matter.
An aspiring owner should also understand the contractual side of operating with a surety. Before signing, review underwriting authority, reporting duties, financial obligations, record requirements and the allocation of losses with appropriate professional advisers. A business plan based only on expected premium receipts leaves out the obligations that can arise when a bond becomes a problem.
State lines require another check. A California credential should never be treated as permission to conduct regulated activity everywhere. North Carolina, for example, has its own bail licensing framework under Section 58-71-40. Before accepting work involving another state, determine what activity is contemplated, which jurisdiction regulates it and whether locally authorized professionals are needed. Expansion should follow verified authority, not an assumption that neighboring markets operate alike.
Learn to Explain the Transaction Under Pressure
In the hypothetical career change, the former paralegal’s first difficult client conversation may not concern a court rule. It may involve a family member asking why money is still owed after the defendant returns home. That question tests whether the agency explained the transaction clearly before collecting payment.
In California, the bail amount, the premium charged for the bond and collateral securing obligations are different things. The Department of Insurance explains those distinctions in its consumer overview: https://www.insurance.ca.gov/01-consumers/170-bail-bonds/. An owner should build intake explanations around the actual approved terms, not a blanket statement that everyone pays the same percentage. Premium refunds depend on approved terms and applicable law; collateral requires separate accounting and handling.
Release timing also needs careful language. Posting a bond does not give the agency control over jail processing, other holds or every condition affecting release. Staff should explain what has been verified, what remains pending and when they will provide another update, without promising a release hour.
Payment plans deserve equal attention. Signatures alone do not establish that every required consumer financing notice has been provided. California agreements may require analysis under Civil Code Sections 1799.90–1799.104. Have qualified counsel review the documents and workflow, including when disclosures are delivered and how the agency retains evidence of delivery.
Replace Personal Memory With Case Controls
Paralegals often bring strong deadline habits into agency ownership. The challenge is turning those habits into a system another employee can follow. Each active bond needs a reliable record of the defendant, court, case information, relevant obligations, communications and supporting documents. Changes should be traceable, and important tasks should have both an assigned person and a backup.
California forfeiture work particularly rewards disciplined tracking. Under Penal Code Sections 1305–1308, nonappearance, a declaration of forfeiture, notice, potential relief, possible extension and judgment are distinct events. They should not be compressed into one generic countdown. An agency should have counsel establish how applicable dates are calculated and reviewed for the actual file, rather than relying on a universal deadline measured from a hearing.
Client reminders can support attendance, but they do not replace verification or resolve every missed appearance. Confirm contact details, document communications and establish an escalation path for returned messages or conflicting court information. Review open files regularly. The owner should be able to identify unresolved issues without reconstructing a case from scattered texts and someone’s recollection of a phone call.
Build Financial and Information Controls Together
A new owner needs to know more than how much money entered the bank account. Premium receivables, collateral obligations, operating expenses and potential bond exposure represent different parts of the business. They need records that allow the owner and qualified advisers to understand what was collected, why it was collected and what obligations remain. Money held as collateral should not be treated as ordinary revenue.
Information requires similar discipline. Bail files can contain identity documents, financial details, addresses and information about relatives who are not defendants. Collect only what the operation legitimately needs, restrict access by job function and establish retention and disposal practices consistent with applicable obligations. Employees should not keep uncontrolled copies of client files on personal devices simply because doing so is convenient.
The Federal Trade Commission’s business guidance provides a useful foundation for data minimization, access controls, retention practices and incident response: https://www.ftc.gov/business-guidance/resources/protecting-personal-information-guide-business. California privacy compliance needs a separate coverage analysis; the CCPA does not automatically apply to every bail agency. Whatever the applicable legal framework, the owner needs a plan for responding when information is misdirected, lost or accessed without authorization.
Set Boundaries Before a Difficult File Tests Them
Unpaid premium and concerns about a defendant’s appearance can arise in the same file, but collections and surrender authority are separate issues. Staff must not threaten arrest or surrender to pressure someone into paying. Establish a lawful collections process and refer questions about surrender authority to qualified counsel before anyone acts.
Recovery work requires its own authorization checks. California requires recovery licensure; a training certificate alone is insufficient. Applicable requirements also address conditional authority, written authorization, identification and local notification. None creates blanket police powers or nationwide reciprocity. Verify current requirements through the Department of Insurance: https://www.insurance.ca.gov/0200-industry/0050-renew-license/0200-requirements/Bail-Fugitive-Recovery-Agent.cfm. Selecting a recovery professional should include checking current credentials, insurance where appropriate and written responsibilities.
The practical path from paralegal to owner is therefore a staged one: verify authority, secure professional review, test intake explanations, establish financial controls and rehearse case handoffs before opening. Courtroom experience can make an owner attentive to details. A sustainable agency turns that attention into repeatable procedures, clear boundaries and records that remain understandable when a client, regulator, surety or attorney needs answers.
Get the Weekly Brief
More in this section
Three Generations Behind the Counter: What a Family Bail Agency Must Learn to Last
A multigenerational bail agency needs more than a familiar name across from the jail. Through an explicitly hypothetical Texas family business, this article examines how judgment, documentation, client communication and succession planning must change as responsibility passes from one generation to the next.
Bail Bonds Magazine Staff · Oct 28, 2026 · 6 min
Why Patience Matters in Bail Recovery
A difficult recovery assignment is not solved by an app alone. An illustrative case shows how verified information, lawful authority, careful communication and disciplined documentation can matter more than constant activity—and why patience must never become neglect of court deadlines.
Bail Bonds Magazine Staff · Oct 27, 2026 · 6 min
Close Calls in Bail Work: Lessons in Verification, Documentation and Knowing When to Stop
A difficult night can expose weak handoffs, unclear authority and promises an agency cannot keep. These illustrative situations show how bail professionals can slow decisions, protect client information and recognize when a supervisor, licensed specialist or legal counsel should take over.
Bail Bonds Magazine Staff · Oct 23, 2026 · 6 min